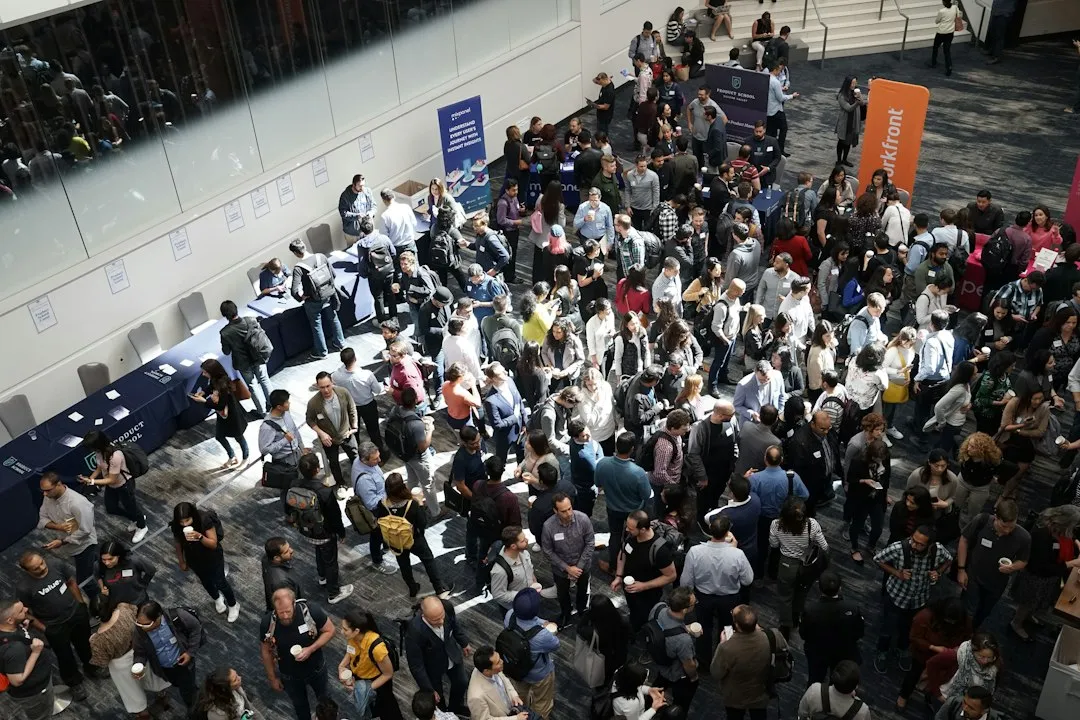
The NFDA Annual Convention & Expo runs October 25–28, 2026, in Charlotte, North Carolina. Over 300 vendors. Thousands of funeral professionals. Four days of sessions, panels, and expo floor conversations that reveal more about the state of the death care market than any broker report you’ll ever read.
Most prospective buyers don’t attend. They assume it’s for licensed funeral directors — people already in the industry. And the ones who do show up wander the expo floor collecting brochures and stress balls, missing the real opportunity entirely.
Here’s what the convention actually is: a structured intelligence-gathering operation disguised as a trade show. Retiring owners walk the floor. Vendors know exactly who in your target geography is expanding, struggling, or quietly shopping their business. Session topics telegraph where the industry is headed — and which business models are about to get repriced.
If you’re serious about acquiring a funeral home in the next 12 to 24 months, Charlotte is the single highest-ROI four days you’ll spend this year. But only if you work it like a buyer, not a tourist.
Why a Prospective Buyer Belongs at the NFDA Convention
You’re not a funeral director. You don’t embalm. You’ve never arranged a service. Why would you spend $2,000–$3,000 on registration, airfare, and a hotel in Charlotte?
Because the convention solves three problems that are nearly impossible to solve from behind a laptop.
Problem 1: You can’t find sellers. The best funeral home acquisitions never hit the open market. Owners who are thinking about selling — not ready, just thinking — attend the convention every year out of habit. They’re in the hallways between sessions. They’re at the hotel bar at 9 PM. They’re not listed with a broker yet. They might not even admit they’re considering it. But the signals are there if you know what to look for.
Problem 2: You don’t understand the local market. Your deal sourcing playbook can tell you which funeral homes exist in your target geography. It can’t tell you which ones are losing share, which ones can’t find staff, which ones are running outdated software and haven’t invested in the business in five years. Vendors can.
Problem 3: You don’t know what you don’t know. Sessions on AI adoption, the staffing crisis, regulatory shifts, and cremation trends give you the vocabulary and context to evaluate an acquisition like someone who’s been in the industry for twenty years. That knowledge gap is what sellers exploit in negotiations — and what brokers charge a premium to bridge.
Pre-Convention Preparation: The Week Before Charlotte
Don’t show up cold. The four days move fast, and the buyers who extract the most intelligence are the ones who arrive with a plan.
Register Early and Choose Sessions Strategically
Registration is available on the NFDA website. The expo-only pass is cheaper, but the full registration is worth it — sessions are where you pick up market direction, and the networking events are where deals germinate.
Review the full session schedule and flag anything related to:
- Succession planning and business transitions — these rooms are full of owners thinking about their exit
- Staffing and workforce development — tells you which markets are critically short on licensed directors
- Technology adoption — reveals who’s investing in their business and who’s coasting
- Regulatory and compliance updates — the FTC Funeral Rule changes and state-level regulatory shifts that affect valuation
- Cremation trends and alternative dispositions — the single biggest variable in any funeral home’s future revenue model
Skip the sessions that are purely operational unless they cover a topic you’ll need to evaluate in due diligence. Your time on the expo floor and in hallway conversations is more valuable than sitting through a presentation on embalming technique.
Build Your Target Lists
You need three lists before you land in Charlotte.
List 1: Owners you want to meet. If you have target markets, research the funeral homes in those areas. Check who’s registered or presenting. Look for owners who’ve been in the business 25+ years — they’re in the succession planning window.
List 2: Vendors who serve your geography. Casket suppliers, software companies, answering services, preneed providers, cremation equipment manufacturers — these companies have sales reps who cover specific territories. They know every funeral home in their territory by name. Find the vendors whose footprint overlaps your target markets.
List 3: Sessions that map to your knowledge gaps. Be honest about what you don’t understand. If you’ve never looked at a funeral home’s technology stack, attend the software sessions. If you don’t understand the preneed-to-at-need conversion cycle, find the session that covers it.
Prepare Your Cover Story
You’re not lying. You’re being strategic about disclosure.
“I’m exploring opportunities in the death care space” is true and reveals nothing actionable. It invites conversation without broadcasting that you’re an active buyer with capital ready to deploy. The moment you announce you’re shopping for a funeral home, every conversation changes — vendors pitch you, owners get guarded, and brokers materialize from behind potted plants.
Better framing: you’re researching the industry. You’re interested in the business side of death care. You’re evaluating whether this is the right space for your next venture. All true. All calibrated to invite candor rather than salesmanship.
Day-of Strategy: Working the Convention Like a Buyer
Morning: Sessions for Market Intelligence
The convention’s first sessions each day are your classroom. Attend them with a specific question in mind: what is changing in this industry that will affect the value of a funeral home I buy in 2027?
Sessions that reveal market direction:
- AI and technology panels — Listen for which tools funeral homes are adopting and which they’re resisting. A business that hasn’t adopted modern arrangement software, digital GPL pricing, or online preneed sales is either a turnaround opportunity or a money pit. The gap between early adopters and laggards is widening, and it directly affects valuation.
- Staffing and workforce sessions — The labor market for licensed funeral directors is the single biggest operational risk in any acquisition. Listen for regional specifics. A market where three mortuary schools closed and the average director age is 58 is a different acquisition than a market with a pipeline of new graduates.
- Cremation and alternative disposition panels — Cremation rates vary wildly by geography, from 45% in parts of the South to 80%+ on the West Coast. A funeral home’s cremation mix determines its revenue ceiling. Sessions on this topic reveal where rates are headed in specific markets.
- Regulatory updates — State-level changes to licensing requirements, preneed trust regulations, and environmental rules can create compliance costs that aren’t on the balance sheet yet. These sessions tell you what’s coming before it hits.
Take notes on specific data points, not general impressions. You want numbers: cremation rate trajectories, average revenue per call by region, staffing cost increases, technology adoption percentages. Industry publications like Funeral Director Daily cover these trends, but convention sessions surface the data before it hits print.
Afternoon: The Expo Floor Is Your Intelligence Operation
The expo floor is not for collecting brochures. It’s for having conversations with people who know things about funeral homes in your target markets that you can’t learn any other way.
Your expo floor priorities, in order:
1. Software vendors. Companies selling funeral home management software — arrangement tools, accounting systems, website platforms — know their customers intimately. They know who’s growing, who’s struggling to pay their subscription, who’s still running the business on paper. They know which funeral homes have modernized and which are running twenty-year-old systems.
Ask: “What’s the biggest challenge your customers in [state/region] are facing right now?” Listen for mentions of owner burnout, difficulty hiring, declining call volume, or resistance to change. These are all pre-sale indicators.
2. Casket and merchandise suppliers. The big casket companies — Batesville, Matthews Aurora, Wilbert — have territory reps who visit every funeral home in their region multiple times a year. They see the inside of the business. They notice when a funeral home stops ordering premium caskets and shifts to rental caskets for cremation services. They know when an owner starts talking about retirement.
Ask: “How has the product mix shifted in [region] over the past few years?” The answer tells you about cremation trends, pricing pressure, and which funeral homes are adapting versus which are in decline.
3. Answering services and call centers. These vendors handle after-hours calls for funeral homes. They know call volume. They know which funeral homes are so short-staffed that every call goes to the answering service. They know which owners pick up at 2 AM because they can’t afford another director.
Ask: “What’s the typical call volume pattern you see for a funeral home doing 200 calls a year?” This gives you a baseline to compare against anything a seller tells you later.
4. Preneed insurance and trust companies. Preneed providers know the preneed book — the single most valuable and most misunderstood asset in any funeral home acquisition. They know which funeral homes have large, well-funded preneed books and which have been selling preneed contracts that are underfunded relative to current service costs.
Ask: “What are you seeing in terms of preneed contract fulfillment rates versus original face values?” The answer tells you whether preneed books in your target market are assets or liabilities.
5. Cremation equipment manufacturers. If a funeral home is buying a new retort, they’re investing in the business. If they’re patching a thirty-year-old unit, they’re running out the clock. Equipment vendors know who’s investing and who isn’t.
Networking Without Announcing You’re Shopping
The most valuable intelligence at the convention comes from conversations with funeral home owners themselves. But the moment you say “I’m looking to buy a funeral home,” the dynamic shifts. Owners either clam up or start selling you on their business at an inflated price.
The goal is to have conversations that surface whether someone might sell — without ever asking directly.
Conversations That Surface Sellers
The succession question: “Do you see your kids coming into the business?” This is the single most revealing question you can ask a funeral home owner. If the answer is no — and it usually is — you’ve identified someone who will eventually need an exit. The follow-up question matters: “So what’s your long-term plan?” Some will say they haven’t thought about it. That’s your signal.
The staffing question: “How’s staffing been for you?” An owner who can’t find licensed directors is an owner whose quality of life is deteriorating. They’re working nights. They’re missing family events. Every unanswered 2 AM call pushes them closer to selling. Understanding seller psychology means recognizing these pressure points.
The investment question: “Have you upgraded your technology recently?” Owners who’ve stopped investing in the business — no website refresh, no new software, no facility improvements — are psychologically preparing to exit. They’ve stopped spending money on a business they don’t plan to own in five years.
The market question: “How’s your market been — are you seeing growth or is it flat?” Owners in declining markets may be more motivated to sell before the numbers get worse. Owners in growing markets who can’t staff up to meet demand are frustrated in a different but equally sellable way.
The Hotel Bar at 9 PM
This is not a joke. Some of the most candid conversations at any industry convention happen after the sessions end and the expo floor closes. Funeral home owners — particularly the ones who’ve been coming to the NFDA convention for decades — unwind in the hotel bar or restaurant.
Buy someone a drink. Ask about their career. Listen. The owner who’s been doing this for thirty-five years and just had a hip replacement is telling you something when he says, “I don’t know how many more of these conventions I’ve got in me.”
Don’t pitch. Don’t hand out a business card that says “funeral home acquisitions.” Just listen and be genuinely interested in their story. Plant seeds. Exchange contact information as someone who’s “interested in the industry” and follow up after the convention.
Competitive Intelligence to Collect
Come home from Charlotte with a notebook — physical or digital — full of specific, actionable intelligence. Here’s what to capture:
Market-Level Intelligence
- Cremation rate trajectories by state and region — where rates are headed matters more than where they are today
- Average revenue per call — what funeral homes in your target market are charging, and whether prices are rising or compressing
- Service mix shifts — the ratio of full-service funerals to direct cremations to celebration-of-life events
- Staffing availability by market — which regions are critically short on licensed directors and which have adequate pipelines
- Technology adoption rates — what percentage of funeral homes in your target market have modernized versus running legacy systems
- Regulatory changes on the horizon — pending state legislation or rule changes that will affect operating costs
Business-Level Intelligence
- Specific funeral homes showing pre-sale signals — owners near retirement, understaffed operations, businesses that have stopped investing
- Vendor relationships — which suppliers serve your target market and how their customer base is shifting
- Pricing data — what the competitive landscape looks like for general price list items in your geography
- Preneed market health — whether preneed books in your target area are properly funded or underwater
- Consolidation activity — whether private equity or regional consolidators are active in your target markets
Relationship Intelligence
- Owners you connected with — names, funeral homes, what you discussed, any follow-up commitments
- Vendors with territory knowledge — sales reps who cover your geography and are willing to talk
- Industry consultants and advisors — firms like The Foresight Companies that specialize in funeral home valuations and transitions
- Brokers and intermediaries — anyone who mentioned working on funeral home transactions in your area
The Financing Conversation
Financing will come up — either in sessions, at vendor booths, or in conversations with other attendees exploring ownership. The SBA’s lending programs are the most common route for funeral home acquisitions, but the capital stack for a deal this size is rarely just one loan.
If a financing question comes up in conversation, Lendesca.com is a resource that covers the full capital stack for funeral home acquisitions — SBA loans, seller financing structures, working capital lines, and the interaction between them. Having a clear financing picture before you start making offers separates serious buyers from tire-kickers in every seller’s mind.
Know the basics before Charlotte: how much you can deploy, what your SBA pre-qualification looks like, and what deal structures you’re open to. Sellers and their advisors can smell an unprepared buyer from across the room.
Post-Convention Follow-Up: Converting Contacts Into Deal Flow
The convention ends on Tuesday. By Friday, most attendees have forgotten half the conversations they had. Your follow-up speed and specificity is what separates you from every other person who shook hands with that retiring owner.
The 48-Hour Window
Within two days of the convention ending, send a personal email to every meaningful contact you made. Not a form letter. Reference something specific from your conversation.
For owners you connected with:
“Great meeting you in Charlotte. I enjoyed hearing about [specific thing they mentioned — their father starting the business, the chapel renovation, the staffing challenge]. I’d love to stay in touch as I continue learning about the industry. Would you be open to a call in a few weeks?”
No mention of buying. No mention of deals. Just relationship maintenance. The sale — if there is one — happens in three to twelve months, not in the follow-up email.
For vendors with territory knowledge:
“Thanks for the conversation at the booth. The insight about [specific market trend they mentioned] was exactly the kind of context I’ve been looking for. I’m going to be spending more time researching [region]. Would you be open to a brief call to help me understand the landscape better?”
Vendor reps are underutilized intelligence sources. They’ll talk because you’re a potential future customer of theirs — when you own a funeral home, you’ll be buying their products.
For consultants and brokers:
Direct outreach is fine here. These are professionals who facilitate transactions. Tell them your criteria, your timeline, and your financing capacity. Ask about off-market opportunities in your target geography.
Building the Relationship Over Time
The owners you met in Charlotte who might sell in the next two years need to see you as a known quantity, not a stranger with a checkbook.
- Follow them on LinkedIn if they’re active there
- If they mentioned a specific challenge, send them an article about it a month later
- If they’re involved in their state funeral directors association, attend a regional event where you’ll see them again
- Keep notes on every interaction so your follow-up six months later references details they’ll be surprised you remembered
This is how off-market deals happen. Not through cold calls or broker listings. Through relationships built over months where the seller eventually says, “You know, I’ve been thinking about what we talked about in Charlotte.”
The Cost/Benefit Calculation
Let’s be honest about the investment:
- NFDA registration (full): $800–$1,200 for non-members
- Airfare to Charlotte: $200–$600 depending on your origin
- Hotel (3–4 nights): $600–$1,000 at convention-rate hotels
- Meals and incidentals: $300–$500
- Total: $1,900–$3,300
Is it worth it? Run the math against the alternative.
A funeral home broker charges 8–12% of the transaction price. On a $1.5 million deal, that’s $120,000–$180,000. If attending the convention helps you source even one off-market deal over the next two years — a deal where you negotiate directly with a seller you met at the hotel bar — you’ve saved fifty to a hundred times your convention investment.
Even if you don’t source a deal directly from convention contacts, the market intelligence alone changes how you evaluate opportunities. Knowing that cremation rates in your target market jumped 6 points last year, or that three funeral homes in your county are being run by owners over 70 with no succession plan, or that the local answering service is handling twice the call volume for one struggling operation — that intelligence makes you a better buyer on every deal you evaluate.
If you’re casually curious about funeral home ownership, save the $3,000. If you’re deploying capital in the next 12 to 24 months, Charlotte is a rounding error on the deal you’re going to make — and the intelligence you gather there will pay for itself many times over.
Your Charlotte Checklist
Two weeks before:
- Register for the full convention at nfda.org
- Book hotel near the convention center — the closer, the better for hallway networking
- Build your three target lists: owners, vendors, sessions
- Prepare your framing — how you’ll describe yourself and your interest
- Order simple, industry-neutral business cards if you don’t have them
During the convention:
- Attend 2–3 sessions per day focused on market direction
- Spend at least 3 hours daily on the expo floor in targeted vendor conversations
- Take detailed notes after every meaningful conversation — names, funeral homes, key details
- Attend at least one evening networking event or find the hotel bar gathering spot
- Collect business cards and add context notes to each one before bed
Within 48 hours after:
- Send personalized follow-up emails to every meaningful contact
- Organize your intelligence notes into market-level and business-level categories
- Update your target list with new funeral homes showing pre-sale indicators
- Schedule follow-up calls with the three most promising vendor contacts
- Brief your advisory team — attorney, accountant, lender — on what you learned
The convention is four days. The relationships and intelligence you build there compound over months and years. The buyers who acquire the best funeral homes at the best prices aren’t the ones with the most capital. They’re the ones who showed up, did the work, and built the trust that makes a retiring owner pick up the phone and say, “I think I’m ready. Let’s talk.”
Funeral Home Buyer provides educational content for professionals evaluating business acquisitions in the funeral services industry. This article is not legal, financial, or investment advice. Consult qualified professionals before making acquisition decisions.